

Cleo AI: Cash Advance & Money

- 40.24K Reviews
- 4.7
- Downloads
- 5,000,000+
Our take on Cleo AI: Cash Advance & Money from Appgk
I judge money apps by what happens after the first week, not by how polished the opening screen looks. With Cleo AI: Cash Advance & Money, the capability that matters most to me is its conversational approach to everyday budgeting. Instead of making me build a detailed spreadsheet before I can learn anything, it turns questions about spending, saving, and cash flow into a more approachable exchange. That makes the app feel less like a financial filing cabinet and more like a money companion I can consult when a decision is actually in front of me.
Cleo AI is a free finance app from Cleo AI for Android and iOS. It is aimed at people who want help understanding their spending, setting money aside, managing a tight budget, and exploring cash advance or credit-related tools from the same place. Its store summary also points to expense tracking, saving money, and improving a credit score, so this is broader than a simple balance checker. My experience is that its strongest value comes from helping users turn vague worries—“Where did my money go?” or “Can I afford this?”—into a clearer next step.
The app has built a sizable audience, with a 4.7 average from around 148 thousand ratings and over 5 million installs. That popularity does not make it automatically right for everyone, but it does tell me the conversational money-management idea has reached well beyond a small group of enthusiasts. It is free to install, carries a Teen content rating, and the current version is 3.72.0. Those details matter because a younger user or someone new to financial apps may be considering it as a first budgeting tool rather than replacing an established system.
Why the conversational budgeting approach stands out
Traditional budgeting apps usually ask me to think in categories first: housing, food, transport, subscriptions, and so on. That structure is useful, but it can also make the first session feel like administrative work. Cleo AI takes a different route by putting the interaction itself at the center. I can approach a money question in ordinary language, then use the response to decide what to inspect or change. The benefit is not that a chat window magically fixes poor finances; it is that the app lowers the effort needed to begin paying attention.
Best Parts of Cleo AI: Cash Advance & Money
Things to Keep in Mind About Cleo AI: Cash Advance & Money
The real strength is reducing the distance between noticing a problem and acting on it. If I see that my spending is running ahead of my plan, I do not necessarily need another colorful chart. I need to understand what caused the change and what adjustment is realistic before the next bill arrives. A conversational prompt can make that moment feel more immediate. It encourages reflection while the decision is still relevant, rather than waiting until the end of the month to discover that the budget failed.
This is especially useful for people who dislike formal budgeting language. Someone may know that their account balance keeps shrinking but have no interest in maintaining a spreadsheet. A guided exchange can help that person identify patterns, think about a saving target, or examine whether a purchase fits the rest of the month. I would still treat the app as a tool for awareness and planning, not as a replacement for reading statements or understanding the terms of any financial product.
News and Features Related to Cleo AI: Cash Advance & Money

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
The combination of budget support, expense tracking, saving tools, cash advance access, and credit-related guidance gives the app a wider role than a basic expense notebook. That breadth is convenient, but it also means I have to keep the boundaries between those functions clear. Tracking spending is not the same as improving a credit score, and a cash advance is not the same as having more income. The app can bring these subjects together; I still have to make the responsible decision about each one.
What using it feels like in an ordinary week
Imagine I am paid at the beginning of the month and have several automatic bills due soon afterward. Rather than waiting until the balance looks alarming, I can use the budgeting and expense-tracking side to see how much room remains after regular commitments. If an unexpected grocery trip or transport cost appears, the useful question is not simply whether the transaction was “bad.” It is whether the change affects the money needed for upcoming obligations and whether I should slow discretionary spending for a few days.
Don't want to read the full review?
That is where the conversational design can be more practical than a static list. I can use it as a checkpoint before making a purchase, after noticing an unusual expense, or when deciding how much to move toward savings. The workflow I prefer is simple: check the current picture, ask a focused question, inspect the underlying transactions or budget context, and then make one small adjustment. The important part is not having a long conversation. It is using the conversation to create a repeatable decision habit.
A less obvious benefit is that this approach can expose emotional spending without turning the experience into a lecture. If I repeatedly spend more than planned in one area, the useful response is to notice the trigger and change the plan, not pretend the original budget was realistic. A conversational tool may help me articulate that mismatch. I can then set a smaller target, leave room for occasional spending, or decide that a different category needs attention first.
Screenshots
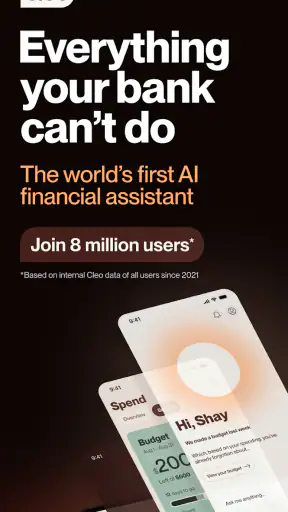
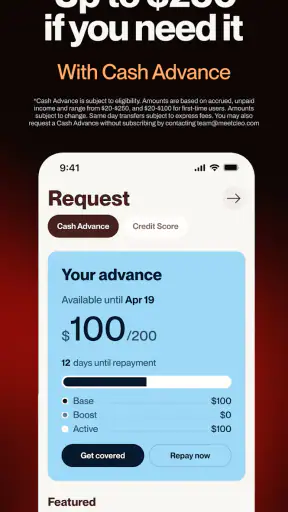
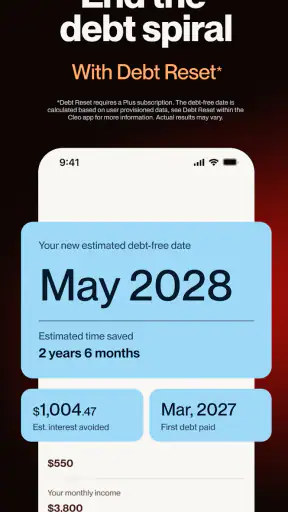
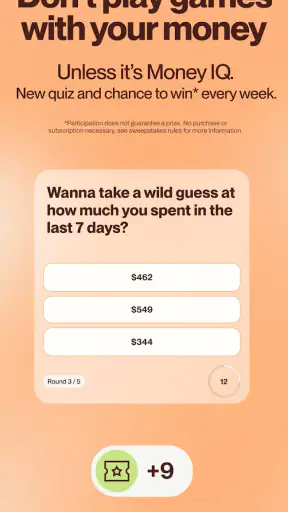
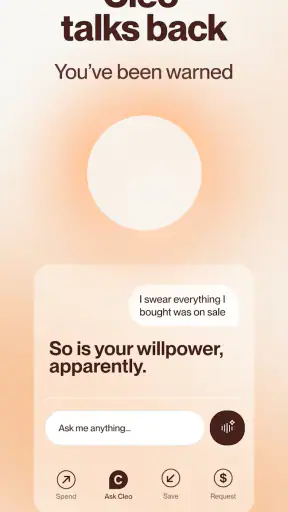
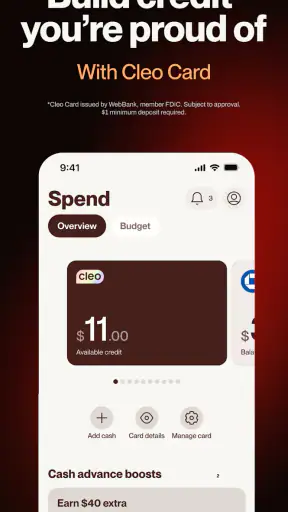
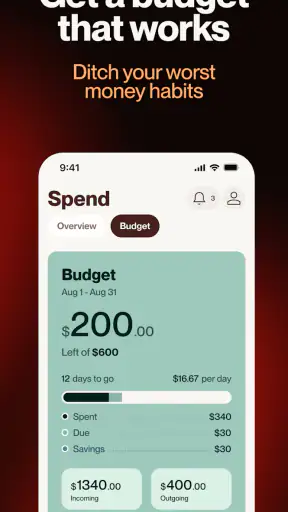
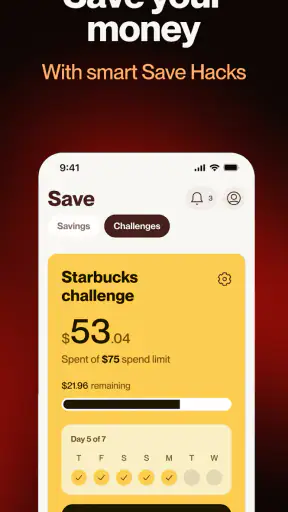
I also found that the app makes more sense when I use it around real financial events rather than opening it randomly. A payday review, a subscription check, a large planned purchase, or an approaching bill gives the interaction a purpose. This is a practical tip that is easy to miss: the app is more valuable when it becomes a short routine tied to a decision. If I only browse it when I am already anxious, I am asking it to solve a problem that should have been monitored earlier.
The most useful scenario for cash-flow pressure
The clearest use case is someone whose income and expenses do not line up comfortably, especially when a normal week includes several small surprises. In that situation, the app’s budgeting and expense-tracking capability can help separate a temporary shortage from a recurring pattern. Before considering a cash advance, I would first use the app to identify what caused the gap, what bills are still due, and whether the next payment will actually restore a stable position.
That order matters. A cash advance may appear attractive when an account is short, but borrowing can postpone rather than solve the underlying issue. I would not use that feature simply because the app makes access feel convenient. I would consider it only after checking the full repayment impact and confirming that the need is genuinely temporary. If the same shortfall happens repeatedly, the more useful response is a revised budget, a lower fixed commitment, or outside financial advice—not repeated advances.
For a person who has enough income overall but struggles with timing, the app can be a useful planning layer. It can help show whether the problem is a few days of cash-flow mismatch or a budget that is structurally too expensive. That distinction is one of the strongest reasons to use the budgeting capability before touching borrowing tools. It turns an urgent feeling into a question that can be examined.
There is also a sensible role for the app in saving. Saving is often presented as a large, ambitious goal, but a person with irregular expenses may benefit more from seeing how small changes affect the next pay cycle. I would use the app to choose a target that does not force me to rely on credit later. The trade-off is that a modest target may feel less impressive, yet it is more useful if I can maintain it without undoing the progress through overdrafts or emergency borrowing.
Where the app can frustrate careful users
The conversational style is approachable, but it is not a substitute for precision. When money is tight, I want to know exactly which transactions are included, how a budget figure was reached, and what a financial product will cost or require. A friendly explanation can help me start, but I would still verify important details in the relevant account information and terms. This is one area where a conventional banking app or a carefully maintained spreadsheet may be better: those tools can present raw records in a more direct, auditable format.
Another trade-off is scope. Cleo AI tries to cover budgeting, tracking, saving, cash advances, and credit improvement in one experience. That is convenient for someone who wants a single place to begin, but it can feel like too much if the only goal is recording expenses. A dedicated spreadsheet may be preferable for a user who wants complete control over categories and formulas. A bank’s own app may be preferable for someone who mainly needs balances, transfers, and official account records. I see Cleo AI as a layer for interpretation and behavior, not necessarily the final authority for every financial detail.
Users should also be realistic about credit-related guidance. Improving a credit score is not an instant result of opening a feature or following a suggestion. Credit outcomes depend on broader financial behavior and the relevant account activity. I would treat the app as an educational and organizational aid, then confirm any important credit decision through the official provider or a trusted financial professional. The app is helpful when it encourages better habits; it is less suitable for anyone expecting a quick score transformation.
Privacy and account access deserve deliberate attention with any finance app. Before connecting financial information, I would read the app’s current permissions and terms, understand what I am authorizing, and use a secure device. I would also avoid treating a conversational answer as proof that a transaction is correct. The convenience of seeing financial information in one place comes with a responsibility to review the connection and keep login details protected.
The Teen rating is worth noting for families. It may make the app feel approachable to younger users, but a teenager should not be left to interpret borrowing or credit-related choices without guidance. The budgeting side can support a useful conversation about needs, wants, and saving. The cash advance side calls for much more caution. I would recommend that a parent or guardian discuss the difference between tracking money and taking on an obligation before a younger user relies on any borrowing feature.
How I would use it without losing control
My preferred workflow begins with observation rather than immediate optimization. I would spend the first few sessions identifying recurring expenses and checking whether the app’s picture matches what I recognize from my accounts. Once that feels reliable, I would choose one target, such as reducing impulse purchases or building a small buffer. Trying to fix every category at once usually creates a budget that is difficult to follow.
A second useful habit is to ask narrow questions. Instead of seeking a broad verdict on my finances, I would focus on a specific decision: whether a planned purchase fits the remaining month, which expense changed most recently, or how a saving target affects upcoming obligations. Narrow questions produce more actionable answers and make it easier to check whether the recommendation matches reality.
I would also separate three moments that are easy to confuse: tracking what happened, planning what should happen, and deciding whether to borrow. The first two are where I see the greatest everyday value. The third deserves a slower process, because convenience can make borrowing feel like ordinary budgeting. Keeping those steps separate helps preserve judgment.
For people comparing it with alternatives, the choice depends on what they avoid. Cleo AI is more inviting than a blank spreadsheet for someone who needs encouragement to start. It can be more interpretive than a bank app that mainly displays transactions and balances. On the other hand, a spreadsheet wins for custom control, while a bank app remains the natural place to verify official account activity. I would choose Cleo AI when I want help turning financial information into a practical conversation, not when I need a complete accounting system.
Who will get the most from it
The best match is a person who knows their spending needs attention but has never maintained a budget consistently. The conversational format can make the first steps less intimidating, and the combination of tracking and saving gives that user somewhere to go after identifying a problem. It is also a reasonable fit for someone managing variable day-to-day expenses who wants to check cash flow before making decisions.
It may help users who prefer prompts and explanations over dense financial dashboards. Someone who often asks, “Can I afford this right now?” may gain more from a guided money check than from another list of transactions. The app is also useful for a person trying to build a regular saving habit, provided the target remains realistic and does not create pressure elsewhere.
I would steer more experienced budgeters toward a different primary tool if they already have a detailed system that works. They may find the conversational layer unnecessary, especially if they need complex custom categories, long-term forecasting, or meticulous reconciliation. I would also advise caution for anyone seeking emergency money repeatedly, anyone who finds borrowing difficult to control, or anyone who wants guaranteed credit improvement. In those cases, the app may reveal the problem, but it cannot remove the financial risk.
After spending time with it, I see Cleo AI as a practical bridge between raw account activity and everyday decisions. Its most convincing contribution is not the promise of doing everything for me. It is the way a simple conversation can make budgeting feel usable at the moment I need it. That can lead to better awareness, more deliberate saving, and fewer casual spending decisions.
My recommendation is therefore specific: try it if you want an approachable way to examine spending and build a money routine, especially if spreadsheets have never lasted in your life. Use the budgeting and tracking functions as the foundation, treat credit guidance as context rather than a guarantee, and approach cash advances with a separate level of caution. For me, the app earns its place when it helps me pause before a financial choice—not when it encourages me to make that choice faster.
Cleo AI: Cash Advance & Money FAQ
What is Cleo AI: Cash Advance & Money, and how does it work?
Cleo AI: Cash Advance & Money is a personal finance app designed to help users monitor spending, manage budgets, and access certain money tools through an AI-powered chat experience. After connecting an eligible bank account, Cleo can analyze transactions, answer financial questions, and provide budgeting insights. Depending on eligibility and current terms, the app may also offer a cash advance feature, but approval, limits, fees, and repayment conditions can vary by user.
Can everyone get a cash advance through Cleo?
No. Access to a cash advance is not guaranteed for every user. Cleo generally evaluates factors such as account activity, income patterns, repayment history, and other eligibility requirements before displaying an offer. The available amount may also differ between users and can change over time. Before accepting an advance, carefully review the repayment date, any optional or mandatory fees, subscription requirements, and the total amount that may be withdrawn from your account.
Does Cleo AI: Cash Advance & Money charge fees or require a subscription?
The app may include free features as well as paid membership plans, depending on the services selected and the current pricing structure. Some cash advance options may be connected to a subscription or may include expedited transfer charges, while standard delivery could follow different conditions. Pricing and terms can change, so check the in-app disclosure and subscription screen before confirming payment. Also review renewal details if you do not want an ongoing membership.
Is Cleo AI: Cash Advance & Money safe to use with my bank account?
Cleo requires users to connect a bank account to provide transaction analysis, budgeting assistance, and eligibility assessments for certain features. As with any financial application, review its privacy policy, data permissions, security information, and the bank-connection provider used during setup. Use a strong password, enable available security protections, and avoid sharing login details outside the official app. No financial app can completely eliminate online security risks, so only connect accounts you are comfortable using.
Will using Cleo affect my credit score?
Using Cleo’s budgeting, spending-analysis, and financial coaching tools does not normally function like applying for a traditional loan. However, credit-related consequences depend on the specific product, eligibility process, and terms presented to you. Read the disclosures carefully to determine whether a feature involves a credit check, reports repayment activity, or is structured differently from a conventional loan. A cash advance should still be treated seriously because missed or unsuccessful repayments can create overdraft problems or additional bank charges.











